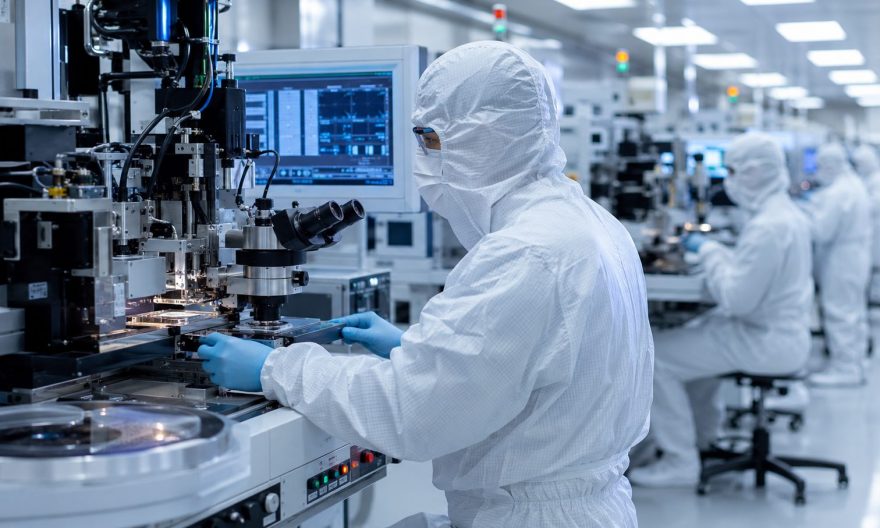
Something significant is happening in U.S. manufacturing right now, and it is not getting the attention it deserves. The sector just posted its sixth consecutive month of expansion, with the ISM Manufacturing PMI coming in at 53.3% for June. New orders expanded for the sixth straight month. Production grew. And the investment commitments flowing into domestic manufacturing are unlike anything the industry has seen in decades.
This is not a temporary bounce. It is starting to look like a structural shift.
The Investment Numbers That Tell the Real Story
This week, Micron Technology announced it is raising its U.S. manufacturing investment to more than $250 billion through 2035, up from an original plan of $170 billion. That is one company. One commitment. In semiconductor manufacturing alone, companies have announced more than $500 billion in private sector commitments to revitalize domestic chipmaking, with projections pointing to a tripling of domestic capacity by 2032 and more than 500,000 jobs created in the process.
The data center buildout is driving a parallel wave of investment in power infrastructure. Transformers, switchgear, power management equipment, and power generation systems are all in multi-year backlog at major equipment manufacturers. Some are sold out for several years ahead. That is the kind of demand signal that reshapes supply chains for a long time.
What Expansion Looks Like on the Ground Right Now
The June PMI report is worth reading carefully. New orders at 56% signal that the demand driving this expansion is not a blip. The Iran conflict and price volatility are still listed as major concerns for manufacturers, and input costs remain elevated after months of pressure. But the overall direction is clear: the U.S. manufacturing sector is in genuine expansion mode, and the companies that positioned themselves for it are benefiting.
The sectors leading growth include technology and semiconductor manufacturing, defense and aerospace, medical devices and pharmaceuticals, and clean energy infrastructure. These are not the traditional manufacturing categories that dominated the last expansion cycle. They are higher-value, more specialized, and more dependent on verified supplier relationships across a complex global supply chain.
What This Means for Sourcing and Procurement Teams
Six months of consecutive expansion changes the sourcing environment in ways that are easy to underestimate. Factories that had available capacity six months ago are filling up. Lead times that were flexible are tightening. Suppliers who were eager for new business are becoming more selective about which customers they prioritize.
The procurement teams that locked in supplier relationships during the slower period are the ones with the most options right now. The ones who waited are finding that the market has moved. This is the moment that validates the advice that sounds obvious in hindsight: build supplier relationships before you need them urgently, not after.
The One Big Beautiful Bill Act, signed earlier this year, also includes tax provisions designed to lower costs and encourage additional manufacturing investment. That policy tailwind is expected to accelerate the investment cycle into 2027 and beyond, which means the capacity tightening happening right now is likely to continue rather than reverse.
Connect with verified manufacturers across all sectors and geographies at Manufacturer.com and build the supplier relationships that position your operation for what comes next in this expansion cycle.